Universal Life Premium Minimization
Our system advises Insurance professionals and Trustees a strategy to maximize Universal Life policy investment stratagies while reducing the financial exposure with our proprietary software that reverse engineers a Universal Life policy illustration and advises our clients to pay only the cost of insurance and invest the difference to ensure the cash value is never at risk.
Why is my Universal Life policy Cash Value at risk?
When you pay the level premiums to age 100 that the carrier states you are paying a small COI building a large cash value that is unrecoverable in the event of early maturity. With our stratagy you pay the COI to the carrier and invest difference with your trusted advisor and your cash value investment is never at risk.
Here is a case study on how our strategy works
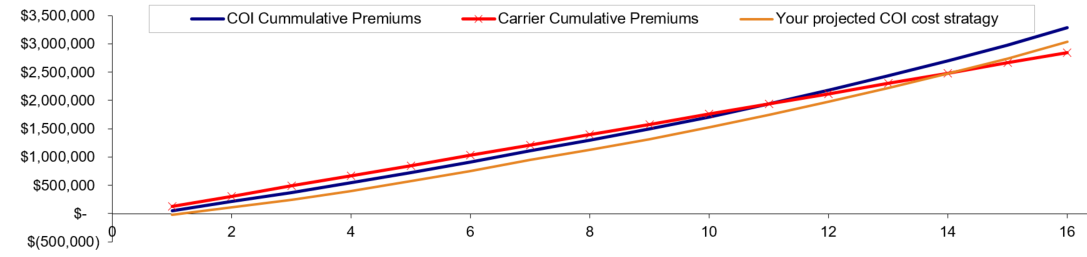
This policy analysis compares the amount of cash value if paying the carrier illustrated level premiums of $181,575 for a policy with a death benefit of $2,000,000 compared to if you reduced the premium payments to only the raw cost of insurance (COI) resulting in a very low premium of $53,285 the first year and paying an increased amount each year following. If you then invested the difference between the carrier illustrated level premiums and the calculated minimum COI premium amount assuming the same interest rate as quited by the carrier your cash value would not be at risk if early death happens. In the initial years the minimized COI cummulative premiums (Blue line) will be lower and the remaining invested amount will be pretected compared to the higher level carrier stated premiums (Red line) amounts
The advantage to paying only the COI and investing the difference seperately in your own personal account is that the money is never at risk of loss to the insurance carrier in case of an early maturity event. For example; if the insured pays the level illustrated premiums to the carrier and builds the cash value in the policy and unfortunately past away early when the cash value was at int highest point the carrier would keep the $225,419 (Gold line) and pay the beneficiaries only the death benefit of $2,000,000. If you pay only the COI and invest the difference sperately you would receive the full death benefit of $2,000,000 while paying similar premium amounts and the client would also have an additional projected additional $196,513 (Blue line) in their personal investment account which would equate to higher pay amount to beneficiaries resulting in an estimated $2,196,513 being paid to beneficiaries.
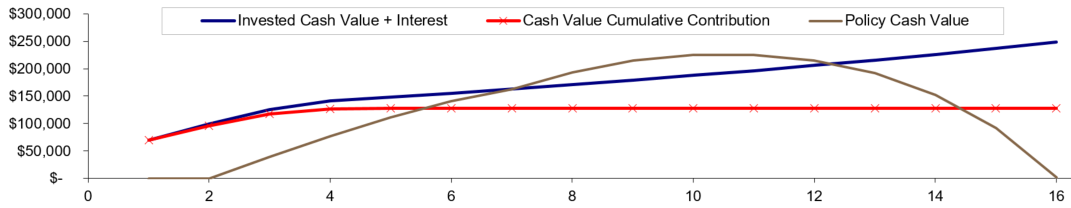
Our preprietary software will ensure your cash value money above the Cost Of Insurance stays in your control and will be passed on to your beneficiaries.


